Market report
Update your view of DIY and DIFM
Explore DIY vs DIFM Q4 2025 for research on European consumers’ choice between doing work themselves and using help. Examine the factors behind that choice and planned projects to refine how you serve different renovation needs.
Blogs I published 06 May 2025 I Dirk Hoogenboom
DIY vs. DIFM in Home Improvement: What Is Actually Happening?
The latest research covered here is the Q4 2025 European Home Improvement Monitor: 58% DIY and 42% DIFM. Earlier findings below are labelled by their research period. DIY and DIFM describe who carries out the work; DIFM includes professional and informal help, and is not a measure of spending.
Let’s start with something you might’ve heard recently – we can’t get anyone to install until October. Our sales are split down the middle. That job was supposed to be DIFM, but the customer decided to just do it themselves. Sound familiar?
Suppliers, category managers, brands and distributors have been hearing and feeling some version of these punchlines for the past couple of years. Everyone expected the home improvement market to lean heavily into DIFM. The logic made sense: aging homeowners, rising complexity, shrinking patience. But reality’s been more complicated because people don’t follow forecasts.
So, what we’re now actually seeing across Europe is more of a tug-of-war driven by age, skill, cost, availability and cultural norms. But when you zoom out, there’s a clear pattern forming. Let’s go over the specifics and break down what’s really going on in home improvement.
Q4 2025: DIY Still Leads at 58%
Let’s get the baseline clear, DIY is still the dominant force… but the lead is shrinking. In 2025, some 58% of home improvement across Europe was still being handled by homeowners themselves. In a vacuum, that looks like a landslide. However, look at the trajectory.
The Q4 2025 report put DIFM at 42%. That is the outsourced share of home improvement work, rather than a claim that professional firms alone account for 42% of spending or customers.
DIY and DIFM need not mean two different customers; the same person can use both. A homeowner might DIY their guest bedroom painting, but hire a pro for their bathroom remodel.
How the Balance Changed: 2019–2025
| Year | DIY | DIFM | Research context |
|---|---|---|---|
| 2019 | 58.7% | 41.2% | 2019 comparison in the 2024 discussion |
| 2022 | 62.7% | 37.2% | 2022 comparison in the Q4 2023 report |
| 2023 | 61.4% | 38.6% | Q4 2023 report |
| 2024 | 60.7% | 39.3% | 2024 discussion |
| 2025 | 58% | 42% | Q4 2025 report |
These are separately published survey snapshots, not shares of people or expenditure. The 2019 and 2022 figures total 99.9%, consistent with the published rounding. The 2022 DIY figure of 62.7% comes from the Q4 2023 comparison; later commentary rounded it to almost 63%. The publications do not establish that every wave uses an identical base, so small differences should not be treated as precise changes in market size.
Before COVID: the Reversal Had Already Begun
The November 2023 analysis looked back at the trend through the end of 2022.
For nearly a decade, we have been monitoring the balance between do-it-yourself (DIY) jobs and do-it-for-me (DIFM) jobs in the European home improvement market. There used to be a slow and steady trend towards more DIFM and, consequently, a gradual decline in the share of DIY jobs. The reasons for this trend were various, but demographics played a major role.
As the population ages, older generations become less capable of doing the home improvement jobs that they used to do themselves. Meanwhile, the younger generation of consumers showed less interest in DIYing on average, resulting in a net decline in DIY jobs and an increase in DIFM. Meanwhile, the market situation was still accommodating in the sense that the labour shortage situation was not that pressing yet, making DIFM a more affordable option.
However, as our results show, the share of DIFM jobs reached its peak in 2018, after which it started to decline. From then through the end of 2022, the share of DIY jobs was on the rise. It is important to note that in 2018 and 2019, there was no pandemic yet. Therefore, the coronavirus crisis cannot be blamed for turning the trend of DIFM versus DIY in the European home improvement market
Q4 2021: Labour Shortages and the Pandemic
One topic that beautifully illustrates the interplay of both trends and events is the tension between Do It Yourself (DIY) and Do It For Me (DIFM), between consumers performing home improvement jobs themselves and the ones outsourcing these jobs to other parties. Knowledge of consumers’ DIY behaviour is essential for the success of strategies of manufacturers and brands of home improvement products.
That is why DIY vs DIFM is a recurring theme of USP Marketing Consultancy’s European Home Improvement Monitor, and the focus of the Q4 2021 report, for which we interviewed 6,800 consumers from 11 countries on how they do or get their home improvement jobs done.
In the years leading up to the Q4 2021 report, we have seen labour shortages increase in the construction and installation sectors in many European countries. Increasing labour shortages make it harder to find a professional to outsource home improvement jobs to and drive up the costs of that labour as well. As a result, more consumers choose to do the jobs themselves.
Aside from the effect of trends like gradually increasing labour shortages and costs, the sudden effect of the pandemic and resulting lockdowns has rocked the boat of home improvement and influenced DIY shares in several ways. As the pandemic raged, people were reluctant to receive professionals into their house, which led many to cancel or postpone larger home improvement jobs that needed the involvement of a professional.
Meanwhile, due to lockdowns, people spent more time at home and could allocate budget that would otherwise be spent in restaurants or on holidays to home improvement. This led to an increase of home improvement jobs in general. Since people had more time on their hands that would otherwise be spent on commuting to work, for instance, they more often picked up the paintbrush or hammer themselves, resulting in more DIY as opposed to DIFM.
The End-2022 View: Experience Gained During Lockdowns
The result was an increase in home improvement jobs done in the European market. Also, many people who would otherwise not do home improvement jobs themselves started doing some DIY jobs during the pandemic. Doing so, they gained some experience, and more confidence and they may have derived joy and pride from doing the jobs themselves.
We know there is a strong correlation between the level of DIY experience and the chances of a person doing home improvement jobs themselves instead of outsourcing them. Chances are high that people who started DIYing during the pandemic continued to do so. So, although the pandemic may not have caused the shift towards more DIY, it acted as a catalyst for that trend.
At the end of 2022, the trend towards more DIY was persisting.
Q4 2023: DIFM Began to Recover
The Q4 2023 DIY vs DIFM report recorded the change in the job mix.
The year 2023 witnessed a pivotal moment in this evolving narrative, with statistics indicating a notable decrease in the share of DIY projects in the total job mix compared to previous years. The proportion of DIY projects declined from 62.7% in 2022 to 61.4% in 2023, while the share of “do it for me” experienced a corresponding increase, rising from 37.2% to 38.6%. This reversal marks the first time since 2019 that the share of outsourced jobs has shown a tangible upward trajectory.
Several factors underpin this resurgence of the “do it for me” mindset. The aging demographic is a primary driver, as individuals recognize the practical necessity of outsourcing tasks that surpass their physical capabilities. Additionally, the aftermath of the COVID-19 pandemic has reshaped consumer behaviours, prompting a surge in DIY efforts, particularly in minor decorative projects. As consumers gradually exhaust these smaller tasks, attention is shifting towards more extensive and intricate home renovations, a domain where professional expertise is often indispensable.
Moreover, there is a discernible trend towards enhancing the sustainability of residential properties. Whether through passive measures such as improved insulation or active interventions like upgrading installations, the pursuit of sustainability is increasingly becoming a priority for homeowners. Such endeavors typically necessitate specialized knowledge and technical proficiency, leading homeowners to enlist the services of professionals.
Despite the burgeoning demand for professional services, the construction and installation sector in Europe faces a formidable challenge in the form of labor shortages. This scarcity of skilled workers poses a significant constraint on the pace of transition towards the “do it for me” paradigm. As labor costs escalate due to the imbalance between supply and demand, the anticipated shift may unfold gradually, with potential reversals prompted by economic dynamics.
2024: What Was Driving DIY?
Make no mistake, DIY is still ahead. In 2024, 60.7% of home improvement work in Europe was being done by the homeowner. So yes, outsourcing was rising, but DIY still accounted for the larger share.
It’s easy to assume that older people outsource – they have more money and less will – and younger people DIY – they have less money, more will and a post-pandemic savviness – but the numbers don’t back that up.
- 35–54 year-olds are the most DIY-active, with 64% doing jobs themselves
- The 55+ group follows closely at 63%
- 18–34 year-olds are least likely to DIY – only 55% of them are up for it
The real split shows up when we look at experience. Of those who describe themselves as having no experience, only 45 percent DIY. Light DIYers are at 63% and experienced renovators at a solid 76%. Meaning… these activities correlate strongly with confidence:
- 76% of self-identified renovators do their own jobs
- 63% of light DIYers do as well
- among those with no experience, only 45% take on the work themselves
What that means: people DIY when they feel like they know what they’re doing. Age alone does not explain it; it also has to do with know-how.
Europe Doesn’t Move as One
The country descriptions come from different periods and use different wording for their survey measures. The 2024 discussion refers to respondents; the Q4 2025 article describes DIY shares. They should not be read as a verified country-by-country time series.
The 2024 Country Picture
In some countries, DIY is still the rule. Germany leads with 70.1% of respondents doing home improvement themselves. France, Austria and Sweden are all in the mid to high 60s. The Netherlands is just above 60%.
Italy, Belgium, and Spain – on the other hand – show far lower DIY rates, in some cases below 50%. The reasons? Many: cultural expectations, local labor dynamics, even regulatory environments. In some regions, hiring help is just how things are done. In others, there’s pride in doing it yourself. And price cuts. All these factor in greatly.
So if you’re working across Europe and thinking about it as a unified field – stop. It’s different behaviors, not one trend. What works in Berlin doesn’t work in Milan.
The Q4 2025 Country Picture
As per usual, talking about a unified European market misses the mark. The DIY culture is a patchwork.
France led the pack in the Q4 2025 discussion with the highest share of DIY. In markets like Germany, Austria and Sweden, we see the DIY rate hovering around the 60-70% mark. These are cultures with a deep tradition of self-reliance and high labor costs that incentivize picking up a wrench.
Move toward the Mediterranean or the UK. The United Kingdom showed the lowest DIY share in the Q4 2025 discussion, while Italy, Belgium and Spain consistently see DIY rates fall below 50%. In these regions, calling a jack-of-all-trades or a professional isn’t a luxury, but the standard operating procedure for almost any task beyond hanging a picture frame.
Who Does the Outsourced Work?
Q4 2021: Respondents’ Outsourcing Choices
For years, the share of home improvement jobs being outsourced was growing, while the share of jobs done by homeowners themselves was declining. As we saw in a previous article, that trend of Do It Yourself (DIY) versus Do It For Me (DIFM) turned around after 2018. Since then, DIY is on the rise again, leading to more than 60% of European home improvement jobs being done by consumers themselves in 2021.
Be that as it may, this still means that about four out of ten home improvement jobs are outsourced to other parties. These other parties may have an influence on product usage and purchase, which is why it is essential for manufacturers and brands of home improvement products to know who these other parties are. For the Q4 2021 report of USP Marketing Consultancy’s European Home Improvement Monitor, we asked 6,800 consumers from 11 countries to whom they outsourced their home improvement jobs.
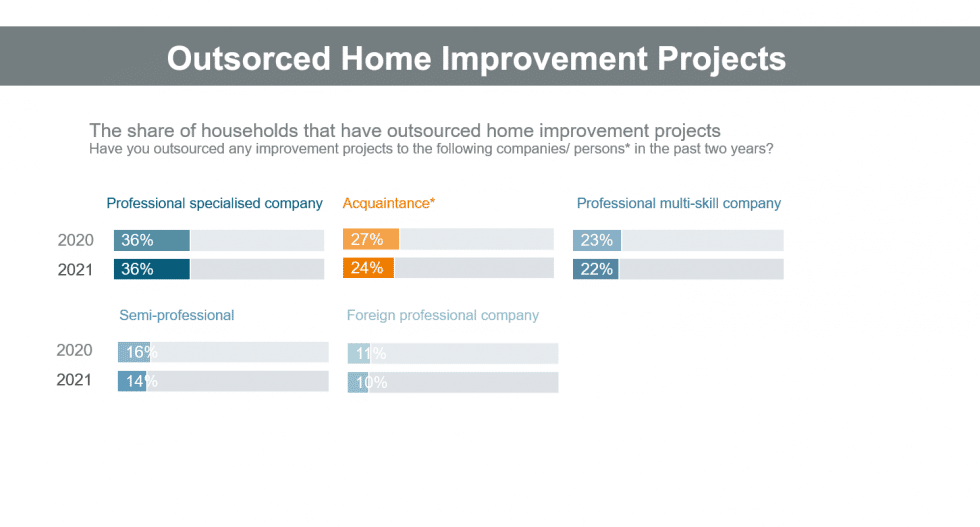
As the graph shows, about a quarter of European consumers reported that they outsourced a home improvement job to an acquaintance. Meanwhile, 36% reported that they outsourced to a professional specialised company, while 22% outsourced to professional multi-skill companies or handymen. 18% outsourced to semi-professionals and 10% to foreign professional companies.
These percentages describe consumers reporting the parties they used. The listed percentages add to more than 100%, so they should not be added into a pie chart or interpreted as mutually exclusive shares of all outsourced jobs.
Clearly, a vast share of outsourced home improvement jobs is outsourced to professionals. These professionals may influence the process, including decisions on products, brands, and points of purchase. For instance, in the recently published European Handyman monitor, we saw that professional multi-skill companies mainly work for private homeowners and report that they have purchasing power in more than half of their projects.
Why the Purchase Channel Can Change
When professionals hired to do home improvement jobs have purchasing power, they will probably use their familiar and favourite purchasing channels. Depending on the specialisation of the professional and the type of home improvement job, these professional channels will range from general building material wholesalers to specialised wholesalers or even purchasing directly from the manufacturer.
This means that brands of home improvement products that naturally rely on purchase channels used by consumers may miss out when home improvement jobs are outsourced to professionals. Even when the share of DIFM declines, the above shows that the share of home improvement jobs outsourced to professionals is quite vast.
These are European averages, though. Shares of home improvement jobs being outsourced differ significantly when zooming in on the countries we covered in this research. Likewise, the types of home improvement jobs and the parties they are outsourced to differ from country to country. For a full overview of consumers’ DIY and DIFM behaviour, including the types of professionals they outsource home improvement jobs to in 11 countries, we refer you to the Q4 2021 report of USP Marketing Consultancy’s European Home Improvement Monitor.
2024: Specialised Companies and Acquaintances
The later 2024 discussion described outsourced jobs, a different measure from the Q4 2021 respondent figures above.
Let’s look at where the outsourced work is actually going. In 2024, 38% of outsourced jobs went to professional, specialized companies, and that’s still the largest market share. But the fastest-growing segment? Acquaintances. Friends, family, neighbors, semi-skilled freelancers. That category jumped significantly, from 19% in 2023 to 29% in 2024. That can’t be ignored.
Why? Again – cost. People want help, but they’re working around the traditional system. Not because they want to, but because they feel they have to.
These aren’t the licensed HVAC crews or full renovation contractors. They’re a neighbor who paints, a cousin who tiles and your best man’s brother-in-law with golden hands, filling the gap left by expensive or unavailable pros.
Q4 2025: The Semi-Professional Middle Ground
There is a growing middle ground that the data is starting to highlight: the semi-professional. This emerging group – made of the side-hustling friends-of-friends, the neighbors’ brothers-in-law or an uncle with hands of gold – has found stronger footing. Why? Because people do want the professional help, but are increasingly looking for it at a more accessible price point than a full-scale construction firm.
2025 Spending Expectations, Recorded in Q4 2024
The following findings are expectations expressed in Q4 2024 about 2025, rather than measured outcomes for 2025 or forecasts for 2026–2027.
Why People Expected to Spend More
The main reasons people said they would spend more on home improvement in 2025 are pretty simple: more work, bigger jobs and higher prices. It’s not about lifestyle upgrades or trend-chasing. It’s just basic backlog, cost pressure and catching up on long overdue maintenance.
Don’t confuse that with high-end project growth, though. The expected spend was functional, not flashy.
Cost and Availability
Labor shortages across much of Europe are still straining capacity. Ask anyone trying to schedule an installer and they’ll most likely tell you there’s a backlog. So, on the off chance that people do look to outsource, they’re immediately hit with high prices, long waits or both.
34% of consumers cited cost as a barrier to outsourcing, a tangible setback pointing them toward cheaper alternatives.
Decorative and Constructive Jobs
What kinds of work are people actually doing?
- Decorative jobs (think paint, flooring, wallpaper, furniture upgrades) are trending up. In Q4 2024, 61% of consumers said they expect to do more large decorative jobs in 2025. For smaller decorative work, it was 57%
- Constructive jobs – both small and large – are flatter. Between 52–60% of people said they expect no increase in activity here
Those expectations pointed to consumers investing in aesthetics and functionality, i.e. things they can tackle themselves or feel confident outsourcing affordably. But major structural or technical projects? They’re more sensitive to cost and labor availability.
This Market Is Spreading Across Different Ways of Working
Forget the idea that DIY is being replaced. It’s not. What we’re seeing instead is that DIFM is diversifying. More people are outsourcing, but not in a traditional sense. They’re using smaller crews, informal help and semi-pros. They’re making different trade-offs than they were five years ago.
At the same time, DIY remains the larger part of the job mix. People who have skills – and especially those who’ve built up some experience, confidence or pastime – are staying in the game. And country by country, it’s playing out in completely different ways.
This isn’t simply a shift from DIY to DIFM. It’s a spreading out into multiple paths. And if you’re only positioned to serve one of those paths, you’re behind.
Conclusion
If you’re still waiting on DIY to collapse or DIFM to become the industry standard across the board, look again. We’re seeing more channels, more players, more grey areas between full-service outsourcing and weekend DIY. This isn’t a bad thing. It’s just different than what we expected, and if you’re willing to track the nuance – who’s doing the work, who’s buying the materials, and what the local habits really look like – you’ll quickly see where the opportunities are moving.
The European renovation market is maturing. We are seeing a more pragmatic homeowner; that’s willing to get their hands dirty and at the same time is smart enough to know when they are out of their league.
Tailored market research
Serve the different ways people renovate
DIY, professional work and informal help can coexist within one household’s projects. USP can help you understand who chooses the products, who carries out the work and what each person needs from your business.
Market Segmentation Research
Identify groups by DIY confidence, outsourcing preferences and project needs so your proposition reflects the different ways consumers arrange home improvement work.
Customer Journey Research
Trace how homeowners and their chosen helpers influence product selection, purchase and installation to find where your brand can provide relevant support.
Product Development Research
Test product and service concepts that address specific project barriers, from clearer instructions for DIYers to convenient solutions for professional or informal helpers.